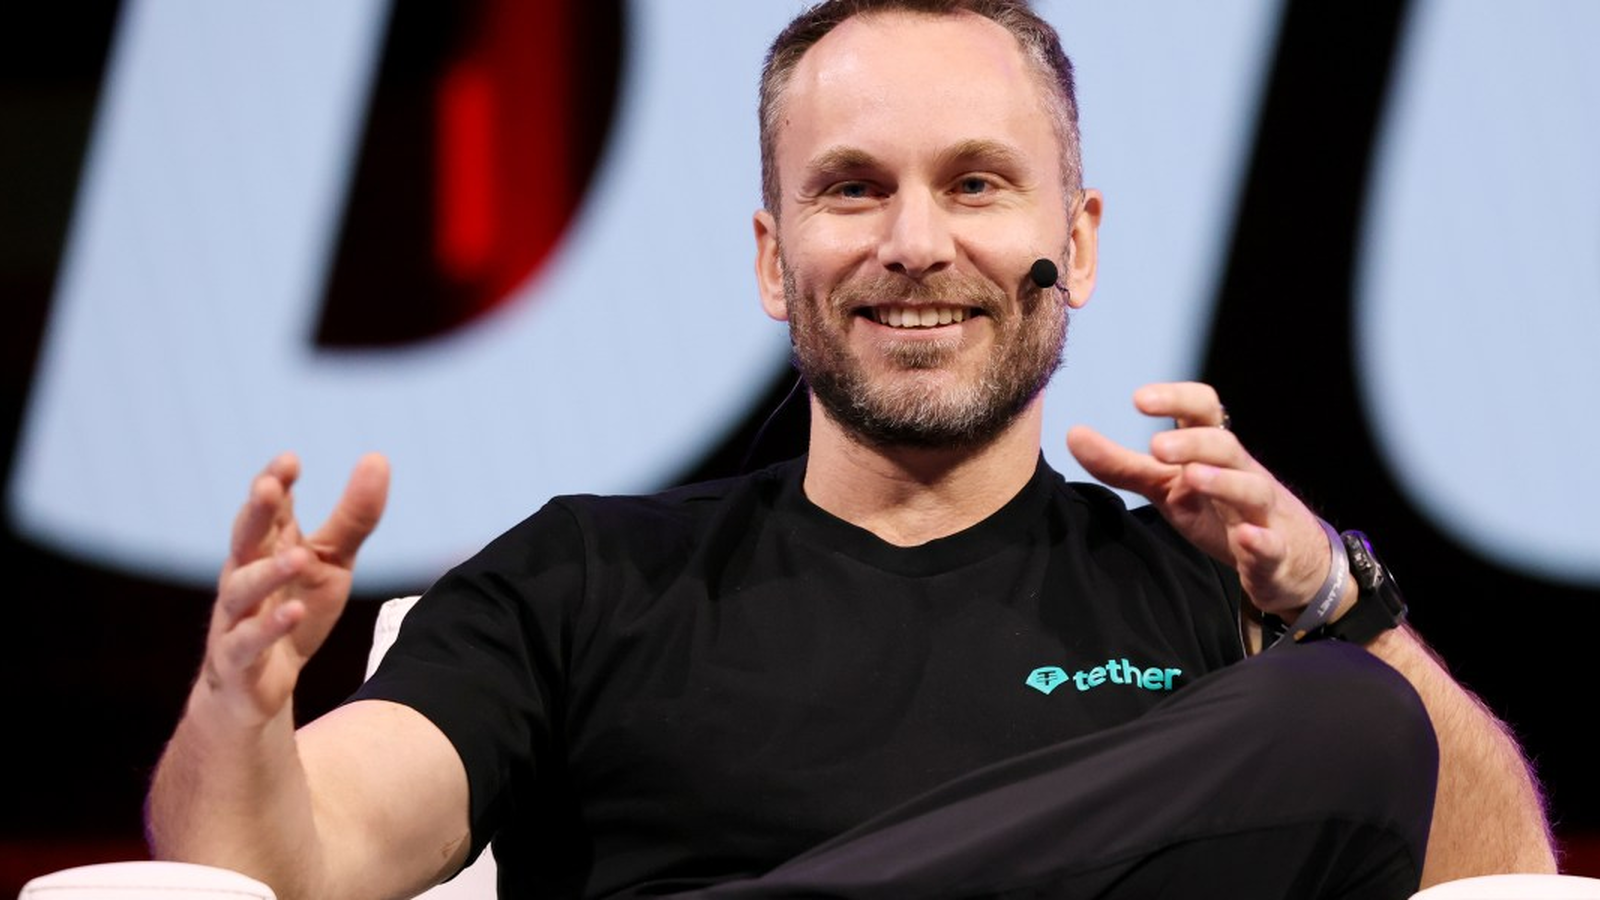
Tether CEO Paolo Ardoino has publicly challenged the Bank for International Settlements' (BIS) recent endorsement of tokenized bank deposits, arguing that fully reserved stablecoins present a safer, more transparent alternative to money held under fractional reserve banking. The exchange at the Jackson Hole Economic Symposium crystallizes an intensifying debate about how fiat-denominated value should be represented on blockchain rails — whether through bank-issued tokenized deposits that remain commercial bank liabilities, or through independently issued stablecoins backed by liquid reserves such as U.S. Treasuries.
What the BIS said
On Aug. 28, BIS General Manager Pablo Hernández de Cos outlined the institution's rationale for favoring tokenized deposits as the primary model for mainstream digital money. He emphasized several properties that, in his view, tokenized deposits preserve better than current stablecoins: redeemability at par, interoperability across jurisdictions and systems, financial integrity, and safeguarding monetary sovereignty in economies that may otherwise experience digital dollarization.
Hernández de Cos described a BIS-preferred model in which tokenized deposits remain on bank balance sheets and settle via central bank accounts. That design, he argued, preserves the 'singleness' of money by ensuring different bank liabilities are ultimately redeemable at par through central bank settlement mechanisms. He also called out technical and regulatory risks associated with public blockchains: cross-chain transfers, bridges and self-custody wallets complicate interoperability and make uniform application of anti-money laundering (AML) and counterterrorism financing controls more difficult.
Key BIS concerns
- Redeemability and peg stability: Stablecoins may deviate from their dollar peg in stress events, making redeemability at par an unresolved issue.
- Interoperability: Public blockchains and cross-chain bridges can introduce fragmentation and settlement complexity.
- Financial integrity and AML: Wide circulation across permissionless networks complicates consistent enforcement.
- Monetary sovereignty: Growing use of dollar-denominated stablecoins outside the U.S. could weaken domestic monetary policy transmission.
Ardoino's counterargument: reserves and safety
Ardoino responded by reframing the debate around reserve composition and transparency. He argued that a properly structured stablecoin — fully reserved and backed by high-quality liquid assets such as U.S. Treasuries — offers depositors a clearer and potentially safer store of value than fractional reserve bank deposits that support lending and credit creation.
He asked a pointed question: why would savers opt to leave assets in fractional reserve products when stablecoins can hold reserves in liquid instruments? In his view, fully reserved stablecoins expose shortcomings in traditional bank funding models and provide an alternative that prioritizes liquidity and straightforward asset backing.
Reserve dynamics at the heart of the debate
- Stablecoins: When issued with dedicated reserve portfolios, stablecoins can hold short-duration government securities and cash-equivalents, making their backing transparent and liquid.
- Tokenized deposits: Funds represented as tokens remain liabilities of the issuing bank and typically continue to support lending and on-balance-sheet activities through fractional reserve practices.
This distinction places the core policy question squarely on whether tokenized bank liabilities or independently collateralized stablecoins better protect savers and preserve systemic stability.
Practical frictions: peg maintenance and interoperability
BIS highlighted operational frictions that can affect stablecoin users. For example, holding USDT while needing to pay a counterparty that accepts only USDC may require a secondary market swap. During liquidity stress, such conversions can trade off-peg and introduce settlement risk. Public blockchain ecosystems also create fragmentation: assets can circulate across multiple chains, necessitating bridges or wrapped versions when moving between networks. Those constructs have historically been vectors of technical risk.
Ardoino counters that these are solvable engineering and market-liquidity problems; he stresses the policy importance of reserve quality and transparency. The debate thus toggles between operational interoperability and the underlying composition of backing assets.
Tokenized deposits advancing in the banking sector
Major banks are actively piloting tokenized deposits and shared token networks. JPMorgan Chase, Bank of America, Citigroup and Wells Fargo are developing a Clearing House deposit token initiative aimed at programmable treasury and cross-border liquidity for corporate clients, targeting an initial rollout in 2027. Meanwhile, SWIFT has launched a blockchain-based shared ledger with a group of global banks to enable round-the-clock cross-border payments using tokenized bank liabilities.
Some challenger approaches attempt to combine both models. Custodia Bank and Vantage Bank are testing a dual-purpose token on Ethereum: within the Hazel network the token behaves as a bank deposit, but when transferred outside it can act like a stablecoin. That hybrid concept seeks to blend on-balance-sheet deposit treatment with off-ledger transferability.
Interoperability and permissioned systems
Hernández de Cos conceded tokenized deposits carry unresolved problems: there is no fully interoperable, multi-bank, cross-jurisdictional ecosystem yet. Many existing implementations are permissioned, raising questions about openness, competition and how closely some architectures might resemble bank-issued stablecoins in practice.
Regulatory and political stakes: deposit flight and lending impact
The stakes of this policy disagreement are high, and U.S. lawmakers are increasingly involved. Banking associations have lobbied to restrict stablecoin reward mechanisms in pending legislation, arguing that generous yields or incentive programs on stablecoin balances could drain deposits from traditional banks. Such outflows could reduce banks' lending capacity, particularly for community banks that rely on stable deposit bases to fund loans.
Citigroup CEO Jane Fraser and other banking leaders have warned that expanded stablecoin rewards may increase banks' funding costs and constrain credit availability. The contention is mirrored in legislative debates over the Digital Asset Market Clarity Act and earlier provisions in the GENIUS Act, which restrict direct interest payments by payment stablecoin issuers but leave room for third-party rewards depending on program structure.
Hernández de Cos added a macro angle at Jackson Hole: if stablecoin issuers park reserves in Treasury securities, they could exert downward pressure on sovereign borrowing costs. Conversely, a shift of deposits out of commercial banks could increase bank funding costs and ultimately lift borrowing costs for households and firms.
Ardoino reframed the same flow of funds as a market correction: if the public decides stablecoins are a safer asset class, then migration of savings into stablecoins is a rational financial behavior. He described the current era as a 'Find Out' phase — a live experiment in which users, markets and regulators will reveal which instruments best serve payments, saving and cross-border commerce.
Global adoption and use cases for USDT
USDT remains the largest stablecoin by circulation and carries significant adoption outside the United States, especially in regions where access to U.S. dollars or traditional banking is limited. Ardoino has positioned Tether as both a dollar-denominated savings vehicle and a payments rail for remittances and commerce in emerging markets. Tether's investments, including a May stake in remittance platform LemFi, illustrate a strategy to cement USDT's role in cross-border corridors across Africa and Asia.
However, the BIS warned that increasing reliance on dollar-denominated stablecoins abroad could create risks for monetary sovereignty and the transmission of domestic policy, a concern commonly labeled digital dollarization.
Use case tension: payments vs. monetary policy
- For users: stablecoins can provide convenient cross-border payments, quick settlement and access to dollar-denominated liquidity.
- For policymakers: widespread external use of dollar-based stablecoins can complicate local monetary control and financial stability frameworks.
What comes next
The debate between stablecoin issuers and the banking sector will shape regulatory outcomes and infrastructure choices in the coming years. Several paths appear plausible:
- Coexistence: Tokenized deposits handle mass retail payments in regulated bank ecosystems while stablecoins serve specialized payments, remittances and markets where dollar access is limited.
- Convergence: Hybrid models and improved interoperability layers could blur the lines between on-balance-sheet tokenized deposits and off-balance-sheet stablecoins.
- Competition and migration: If users prioritize reserve transparency and liquidity, stablecoins backed by high-quality reserves could capture a larger share of dollar-denominated savings and payments.
Policymakers will need to weigh consumer protection, AML compliance, monetary sovereignty and financial stability while fostering innovation in blockchain-based payments. Technical fixes (better bridges, cross-chain standards) and disclosure rules (reserve audits, transparency requirements) are likely to be central to any durable solution.
Conclusion

The Jackson Hole exchange between BIS leadership and Tether's CEO underscores a pivotal policy and market moment. At its core, the dispute is about trust: can tokenized bank liabilities offer the same clarity and safety as fully reserved stablecoins, or do stablecoins expose systemic weaknesses in traditional banking that merit regulatory attention? As tokenization, digital payments and stablecoin adoption accelerate, the design choices made now will influence how fiat money is represented and moved on blockchains for years to come. Regulators, banks, stablecoin issuers and developers will all play decisive roles in shaping that future.
Discussion
Leave a Comment
Comments (3)
Interesting clash. BIS AML and peg concerns are valid, Ardoino's reserve transparency argument is strong. Interop and regs will decide it, imo
wow didnt expect Ardoino to call out BIS like that... if savers shift to stablecoins banks will feel it, big ripple effects
Is BIS sure tokenized bank tokens won't run into the same fragilities? fully reserved stablecoins sound safer but can they scale?