3 Minutes
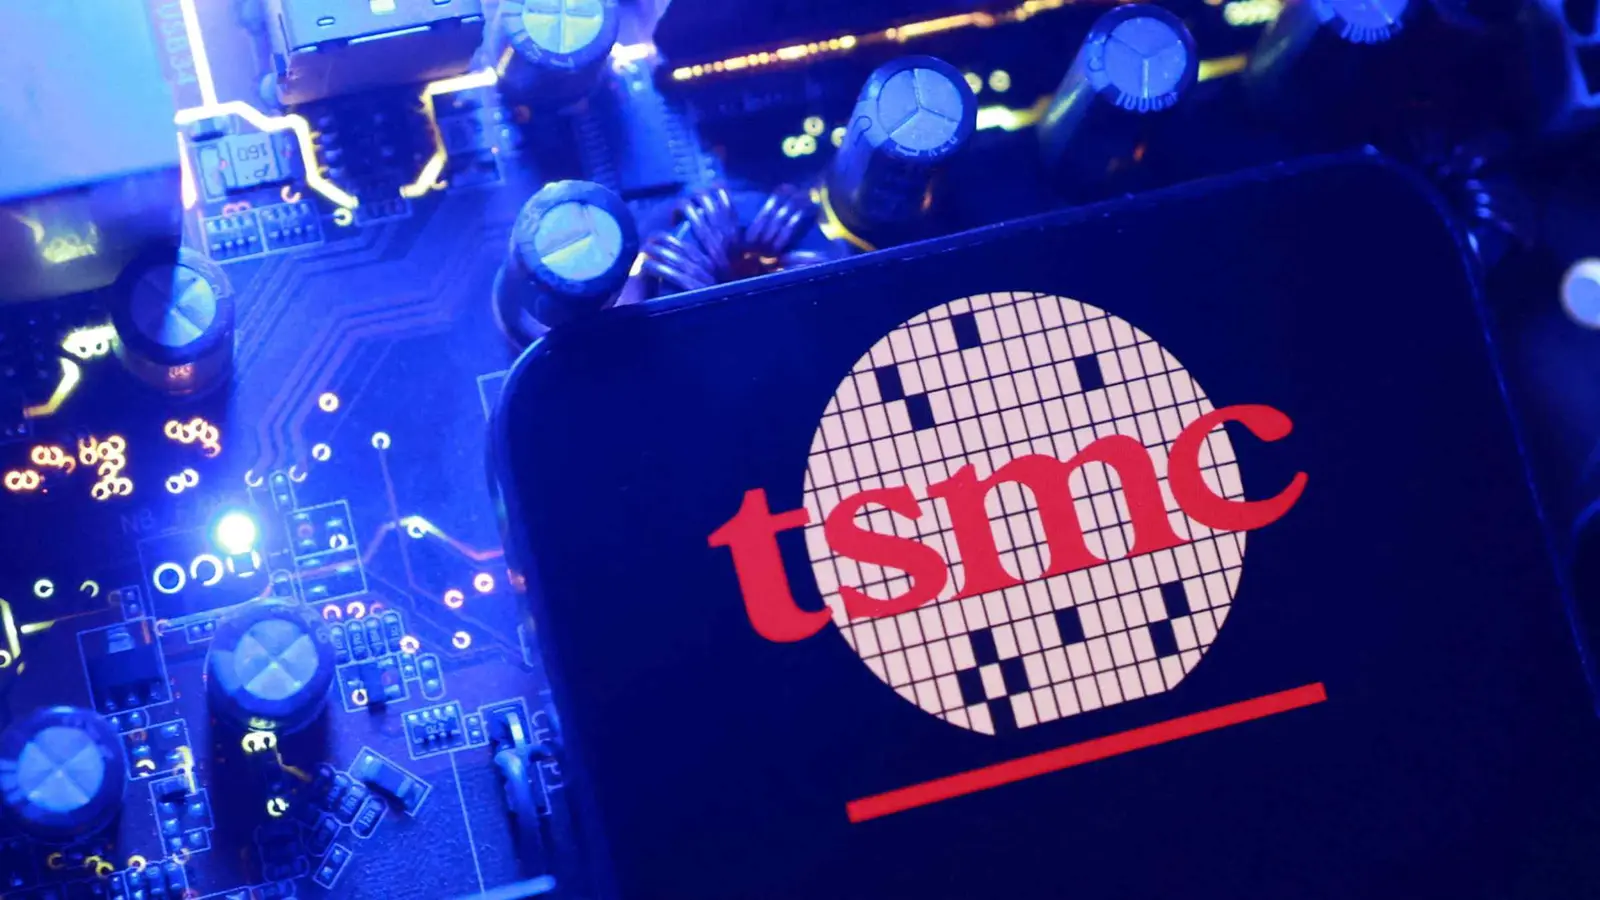
If you thought the semiconductor squeeze was easing, prepare for another jolt. Nikkei Asia says TSMC will raise wafer prices by as much as 10% starting in early 2027, and that ripple is likely to reach every gadget you use.
The hike isn't limited to tomorrow's sci‑fi nodes. Advanced processes will see increases of roughly 5% to 10% depending on the chip type and buyer. But the surprise is that so‑called mature nodes—12nm, 16nm and even 28nm—are in line for up to a 10% rise as well. That means not only flagship phone SoCs like Google’s forthcoming Tensor G11 on cutting‑edge 2nm tech could feel the pinch, but also the workhorse chips inside midrange phones, routers and automotive modules.
Why now? TSMC points to climbing material and equipment costs, plus the heavy price tag of building fabs beyond Taiwan. Expanding capacity across geographies is expensive. Machines that etch patterns at the atomic scale are expensive. Combine those and the math forces a pricing reset.
Who pays? The immediate hit lands on TSMC’s biggest clients—Nvidia, Apple, Qualcomm, AMD and Intel. They will shop around internally and onto other foundries. But those companies rarely swallow costs silently. Higher wafer prices will cascade into more expensive chipsets, and a few months after 2027 begins you could see slightly higher price tags on phones, laptops, tablets and wearables, or thinner margins for device makers.

We’re already watching customers pivot. Apple is reportedly in talks with Intel and Samsung to diversify where it sources silicon. Intel, for its part, allegedly wants to bring 80%–90% of Nova Lake compute‑tile production in‑house on its 18A node—up from an earlier plan where 60%–70% of tiles would be made by TSMC on N2. Qualcomm is said to be weighing a return to Samsung. These maneuvers are practical: when one supplier tightens the screws, others try to loosen dependence.
For the semiconductor ecosystem this isn’t just a price story. It’s a strategic nudge. Foundry relationships, supply‑chain geography, and product roadmaps are all under review. Some companies may accelerate in‑house production. Others will hedge by splitting orders across multiple fabs. End users notice the outcome, not the calculus—either in wallet pain or slower feature rollouts.
The price change is set to begin in 2027, and while its effects will appear gradually, the decision marks a notable shift in how chipmakers and their customers will negotiate the next wave of silicon supply and demand.
Expect a period of adjustment. New contracts will be negotiated. Design choices might shift toward cost‑efficient nodes for certain products. And as fabs sprout outside Taiwan, the industry will find itself paying now for the resiliency it wants later.
So next time you shop for a phone or laptop, ask yourself: is the silicon inside about to cost more than the device suggests?

Leave a Comment
Comments
No comments yet. Be the first.