Omdia forecasts foldable inner-display shipments will rise 44% in 2026 to 29 million units, reversing a 12% decline in 2025.
The forecast covers inner displays rather than finished devices; shipments of display components can precede final-product shipments and may not equal device counts one to one.
Displays for wide foldables will account for 44% of total foldable-display shipments in 2026. The other form factors are larger, squarer book-style panels and smaller flip-style panels.
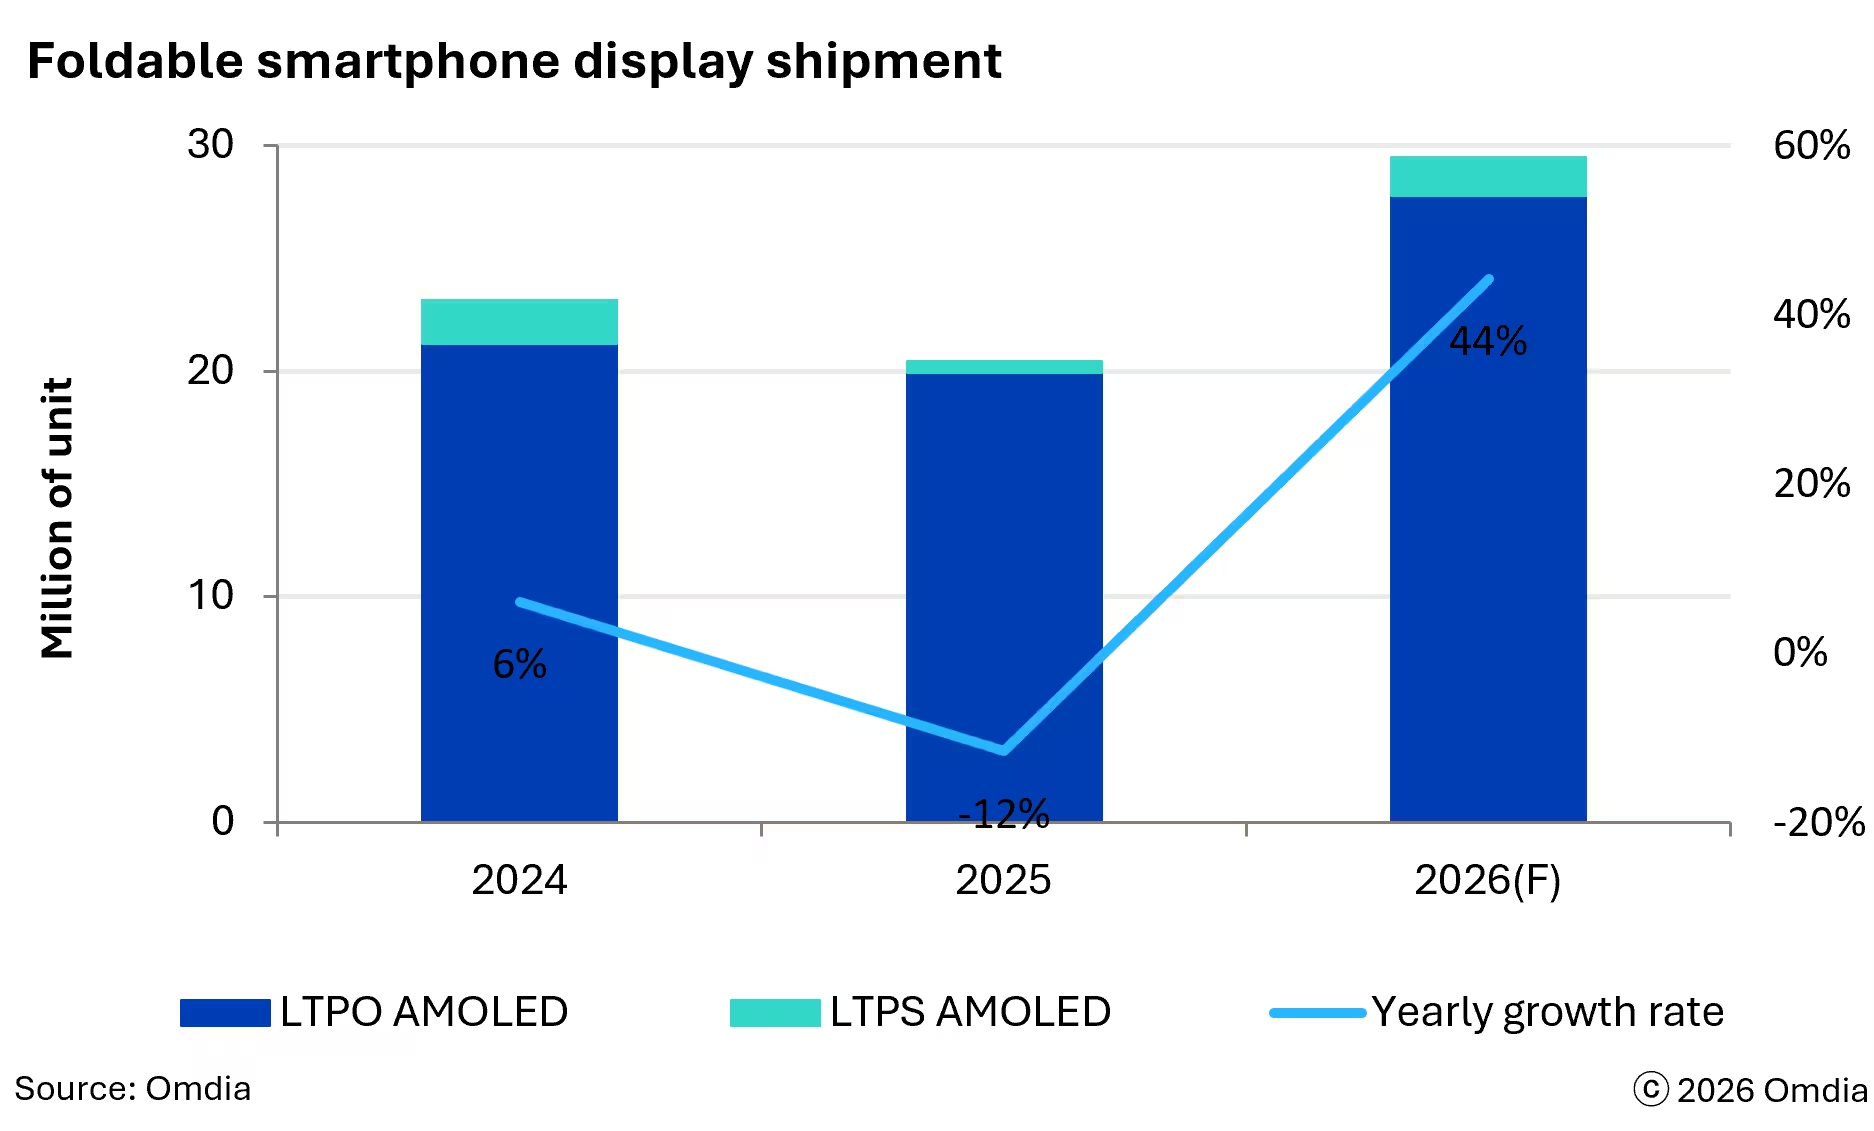
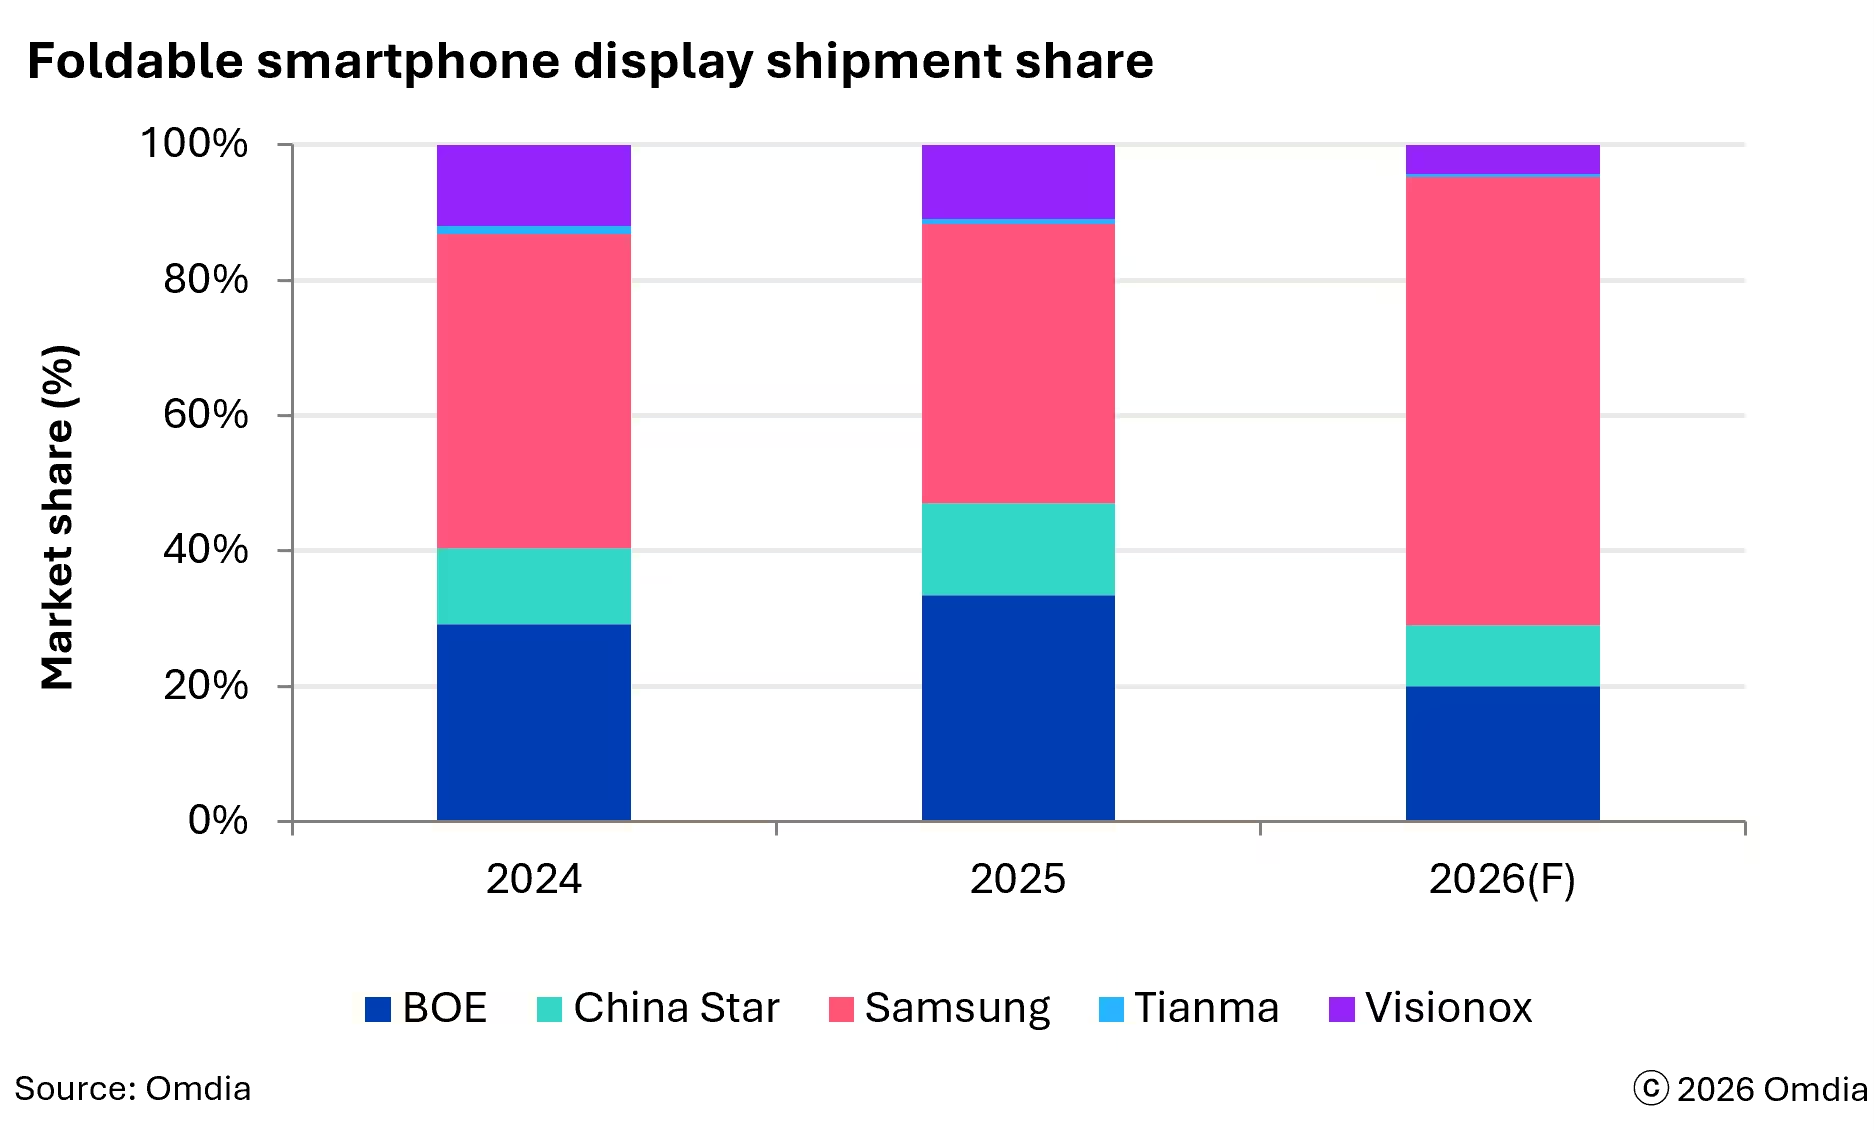
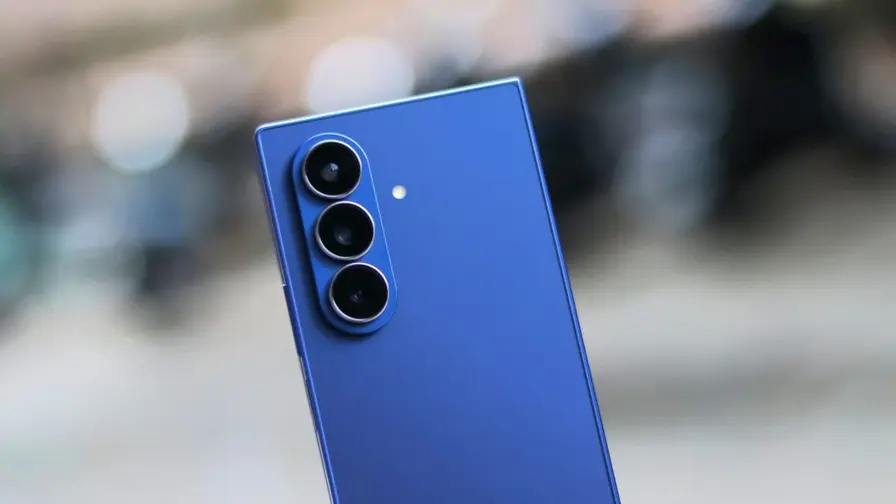
Omdia cites the Samsung Galaxy Z Fold8 and the Apple iPhone Duo as drivers of wide-foldable demand. Samsung Display builds the panels for both models, and Omdia forecasts Samsung Display will hold a 66% market share while BOE, China Star, Tianma and Visionox see their shares shrink.
Omdia analysts say demand for foldables is weak in China at present, but more Chinese manufacturers are targeting the wide foldable segment. Huawei pioneered the form factor, and other makers only recently committed to it.
Omdia expects the vast majority of foldable displays produced in 2026 to use LTPO backplanes. LTPO panels are more expensive than LTPS but offer fine-grained variable refresh-rate control, and manufacturers prefer them, Omdia says.
Because the forecast counts inner displays rather than finished devices, 29 million panels may not translate directly into 29 million shipped foldable phones.
Leave a Comment
Comments
No comments yet. Be the first.