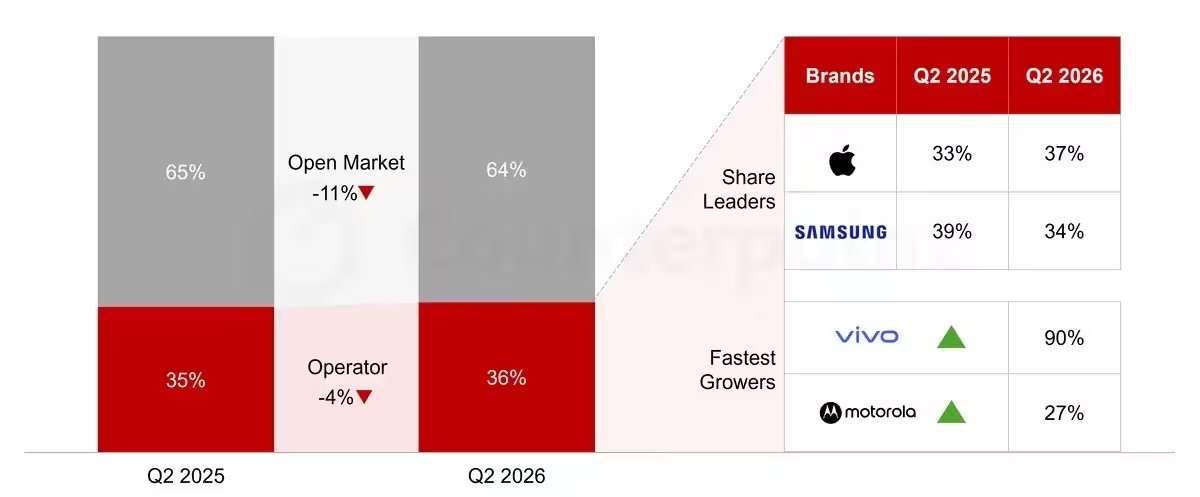
Back in August, Counterpoint Research estimated a total of 35 million smartphone shipments in Europe during the April-June period (Q2). New channel-level data from Counterpoint's Europe Channel Share Tracker shows the open market, meaning independent retailers, recorded an 11% year-on-year decline versus Q2 2025, while the operator channel, meaning carriers, fell by only 4% for the same period. Carriers' shipments fell less than retailers, declining 4% versus an 11% fall for the open market.
Counterpoint analysts explain carriers typically sell higher-end devices compared with retailers. The ongoing memory chip crisis has hit the budget segment hardest, cutting shipments of entry-level devices that are predominantly sold through independent retailers. That concentration of losses in the entry-level tier helps explain why the open market saw a steeper slump than the operator channel.
Brand performance in the carrier channel
Within carrier shipments in Europe, Apple overtook Samsung, taking a 37% share while Samsung held 33%. Counterpoint also identified vivo and Motorola as the faster-growing brands in the carrier segment. Counterpoint analysts say they expect the trend of carrier shipments outpacing retailers to continue.
Leave a Comment
Comments
No comments yet. Be the first.