Arthur Hayes Again Sees Bitcoin at $1 Million by 2030
Arthur Hayes, the former BitMEX CEO and current chief investment officer at Maelstrom, has restated a provocative forecast: Bitcoin could reach $1 million by 2030. Hayes pins the catalyst not on typical macro signals or retail inflows, but on a potential credit shock in debt-financed artificial intelligence (AI) infrastructure. He expects the most dramatic phase of any Bitcoin advance to occur in late 2027 or early 2028, when the strain from AI-related leverage could force policy responses that expand liquidity and benefit crypto markets.
How an AI Infrastructure Credit Cycle Could Boost Bitcoin
Hayes' argument reframes the AI buildout as a credit-intensive construction boom. Data centers, land acquisitions, power hookups, specialized cooling systems and racks of GPUs and accelerators have been financed on long-term repayment schedules. If revenues from AI training and services falter or if computing costs fall faster than expected, those projects may fail to generate the cashflows needed to meet interest and lease obligations. That mismatch between depreciating hardware and long-term debt creates a vulnerability that Hayes likens to a credit crisis.
From equipment depreciation to financing stress
Key to Hayes' thesis is a timing mismatch: cutting-edge processors and AI hardware age quickly while the loans and leases used to finance them often carry multi-year repayment profiles. As newer, cheaper, and more efficient systems enter the market, existing equipment can lose value rapidly. Borrowers on the hook for financing arranged during optimistic revenue projections could struggle when actual demand for compute proves weaker than modeled. Hayes expects that dynamic to crystalize into clear market stress in the latter half of 2027 and into 2028.
Why policymakers might respond with liquidity
Hayes contends that if losses propagate across banks, insurers, private lenders and infrastructure funds, governments and central banks could step in to stabilize markets. He sketches two likely policy responses: direct purchases of computing capacity (making the state a 'compute buyer of last resort') or targeted financial support for insurers and other institutions hit by AI-linked credit losses. Either approach, Hayes argues, would expand monetary liquidity or provide balance-sheet support—conditions he expects to lift Bitcoin prices dramatically.
Market Pathway and Price Expectations
Hayes does not claim a precise timetable for a crisis trigger or a short-term Bitcoin bottom. In prior commentary he outlined a scenario where Bitcoin trades around $60,000–$70,000 during the early phase of AI credit stress, with a possible drawdown toward $50,000 before a sustained rally toward his $1 million target. The underlying premise is that once official interventions or liquidity expansion begin, Bitcoin would benefit as part of a broader revaluation of non-sovereign, scarce monetary assets.
Apollo’s Estimate: Trillions of Dollars in AI Financing
Independent research supports the scale of financing required by the AI rollout. Apollo Global Management, in a noted August briefing, estimated that the AI ecosystem could underpin more than $2 trillion in additional investment-grade debt through 2030. Apollo's chief economist, Torsten Slok, suggested that public investment-grade markets may absorb less than $1 trillion, with the remainder shifting into private placements, infrastructure lending, equipment finance and bespoke credit structures.
Private credit and concentrated issuer risk
Apollo also flagged structural limits in public markets—concentration risk and rating constraints—that may push a large share of AI financing into private credit channels. Using data through July, the firm reported that AI-related borrowing already accounted for nearly 40% of longer-duration investment-grade corporate bond supply. That migration into private debt, where liquidity is tighter and valuation transparency can be lower, raises the potential for sharper stress if assumptions about demand and pricing change.
Regulatory Focus: Insurance Regulators Tighten Rules on Private Credit
US insurance regulators have recently moved to increase transparency and oversight of private credit exposures—an area that intersects directly with Hayes’ concerns. The National Association of Insurance Commissioners (NAIC) has signaled worries about liquidity, valuation practices and sector concentration within private credit funds. These issues have already prompted withdrawal pressures at some retail private credit vehicles and intensified scrutiny of borrowers exposed to AI disruption.
New reporting requirements and accounting changes
Under amendments adopted in 2025, the NAIC now requires private rating rationale reports within 90 days following an annual update or rating change. The mandated reports must contain substantive analytical commentary, improving the traceability of insurer investment decisions in private credit. Additionally, revisions to statutory accounting principles take effect at year-end 2026, enhancing disclosure and valuation protocols for insurers’ private credit holdings. Regulators say these steps are designed to monitor credit quality and valuation methods more closely, not to signal systemic deterioration.
Implications for Crypto Investors and Risk Managers
For crypto investors and risk teams, Hayes' scenario is a reminder to consider macro-financial linkages beyond the direct token market fundamentals. An AI credit shock would be primarily a problem of leverage, collateral revaluation and liquidity, but the knock-on effects—policy easing, balance-sheet support and cross-asset repricing—could materially alter the environment for risk assets including Bitcoin. Investors should weigh exposure to macro liquidity cycles, correlate their crypto allocations with broader credit conditions, and consider scenario planning for both policy intervention and disorderly credit events.
Not all tech companies need to fail
Hayes emphasizes that his thesis does not require a uniform collapse across major AI companies. Rather, the systemic risk comes from the debt underpinning the infrastructure buildout: weaker projects, over-levered developers, and lenders with concentrated exposure. Profitable, well-capitalized AI firms could weather a downturn while smaller or overextended ventures trigger losses for banks, insurers and private credit providers.
What to Watch Next
Key indicators for market participants include slowing announcements of capital spending for AI infrastructure, rising default or distress signals in project finance and private credit funds, and regulatory filings showing increased scrutiny of private credit exposures. Watch the NAIC’s implementation of its new reporting rules at year-end 2026, Apollo and other asset managers’ updates on AI financing flows, and any statements from U.S. authorities about becoming a ‘compute buyer’ or offering targeted insurer support.
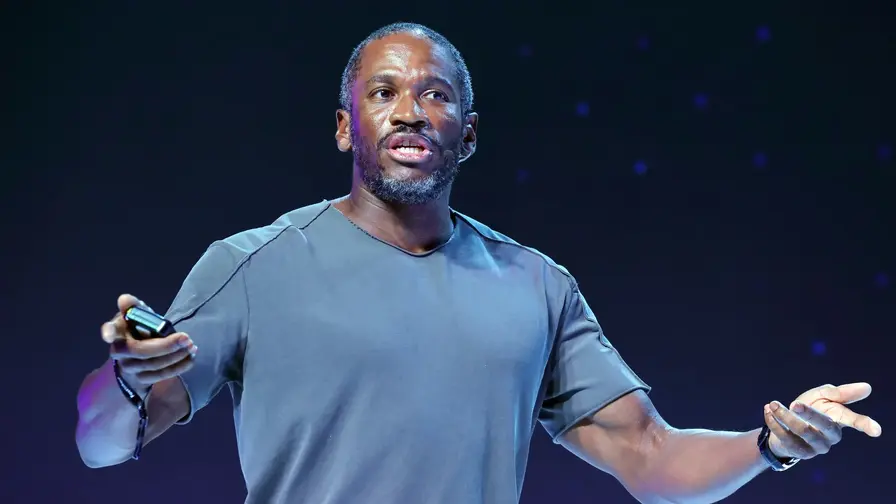
Arthur Hayes' Bitcoin-at-$1M view rests on a chain of events that combines technology depreciation, heavy leverage in AI infrastructure, tightening credit conditions, and ultimately, policy intervention that floods markets with liquidity. Whether markets follow that script is uncertain, but the scenario highlights genuine intersections between AI capital spending, private credit markets, insurance exposures and crypto valuations—making it essential reading for investors tracking Bitcoin, institutional credit risk and potential central-bank or fiscal responses to sector stress.
For readers focused on cryptocurrency price models, Hayes’ thesis adds a macro-financial channel that could amplify demand for Bitcoin as a hedge against monetary expansion. For credit risk managers, it reinforces the importance of examining collateral lifecycles, borrower repayment profiles and concentration risk within private credit portfolios. Ultimately, monitoring both the credit plumbing of AI financing and policy reactions will be critical to assessing the plausibility and timing of any major Bitcoin rally tied to an AI debt episode.
Leave a Comment
Comments
No comments yet. Be the first.